
Your money doesn't disappear. You just don't look.
Too much month left at the end of the money? Write down every expense for seven days, find your leaks and save with the 1% rule. A protocol for your financial foundation.
Key takeaways: Money doesn't disappear. It flows to wherever you are not looking. Write down every expense for seven days, find your three biggest leaks and cut one of them. Then, on payday, you pay yourself first with a standing order, before the rest of the month makes its claims.
At the end of the month you look at your account and wonder where the money went.
It isn't gone. It was spent. By you. In small amounts that don't hurt on their own.
Many people don't have an income problem. They have a flying-blind problem. If you really don't have enough, you don't need a slogan, you need help. More on that below.
Why is there so much month left at the end of the money?
Because you estimate your spending instead of counting it. You know the big amounts by heart: rent, health insurance, the car. The small ones you don't. The subscription that renews itself. The food you order because cooking was too much today. The "just quickly" at the shop round the corner.
On their own these amounts are harmless. Together they are a block of fixed costs you never decided on. Two worked examples with assumed amounts:
- A subscription for CHF 19.90 a month that you no longer use: CHF 238.80 a year.
- Ordering food twice a week for CHF 28 each time: CHF 2,912 a year.
You don't notice because it never happens all at once. That is exactly why it works.
"Beware of little expenses; a small leak will sink a great ship."
Benjamin Franklin, The Way to Wealth (1758)
Why does money belong to your foundation?
Because in the HMF method the foundation consists of finances, relationships and values, and money touches the other two. If you have to plug a hole every month, you rarely decide by your values. You decide by your balance. And arguments about money rarely come to the table alone.
You don't notice a foundation while it holds. You notice it when it cracks. So you look before it breaks.
Order in your money isn't stinginess. It is the precondition for deciding freely.
How do you find out where your money goes?
By writing down every expense for seven days, immediately and without exception. Not in the evening from memory. Immediately. When it comes to money, memory is a generous accountant.
- Amount: to the last centime.
- What: in three words.
- Type: fixed, necessary or wanted.
- Test: Would you buy exactly this again? Yes or no.
Also, once, on the first evening: open your bank statements for the last three months and mark every subscription and every standing order. Look for items you no longer remember. Those are the ones you're after.
A while ago I described this as a daily personal budget. The principle hasn't changed: what you write down, you can steer. What you estimate steers you.
What is a leak, and how do you plug it?
A leak is an expense that comes regularly, looks small and gets a no in the test. After seven days you have a list. Mark the three biggest leaks, calculated over a year.
Then you cut one. Not "use it less", but cancel it. Today. A subscription you "might still need" is one you don't need. Otherwise you would have used it last month.
One leak per week. No more. If you cut everything at once, you'll last two weeks and then treat yourself to a reward that eats it all back up. How not-buying works as an exercise is explained in my no-spending challenge.
How does the 1% rule work for saving?
You save 1% more every day than the day before, in francs. Today = yesterday × 1.01. You calculate daily and transfer weekly, for example every Sunday into a separate savings account.
- Day 1: CHF 2.
- After one month: about CHF 2.70 a day, about CHF 70 in total.
- After three months: about CHF 4.90 a day, about CHF 290 in total.
- After about six months (day 181): about CHF 12 a day and over CHF 1,000 in total. Goal reached.
Worked example, not a promise. Your result depends on you.
At CHF 1,000 you stop increasing. You hold the amount or set your next goal in a different area. If your budget can't carry the increase, start with one franc instead of two. The rule stays the same. Only the pace changes.
And on payday the rule is: you first. A standing order to your savings account, executed the day after your salary arrives. What you don't see, you don't spend.
What if the money really isn't enough?
Then it is not a discipline problem, and you get help early. If you can no longer pay your bills, reminders are piling up or debt collection is looming, don't wait for next month. Points of contact in Switzerland are Schuldenberatung Schweiz and Budgetberatung Schweiz.
This article is not financial advice. It helps you look. For questions about investments, pensions or debt, talk to an independent professional.
How does the planner help?
For the seven days, one of the five tasks on the day page is your foundation task: "Today's expenses recorded". The "1% better" field holds today's savings francs. You write the leak of the week on the week page. If it still isn't cancelled by Sunday, it goes on the red card. The planner is written in German. Details are on the planner page.
Frequently asked questions
Do I really have to write down every small expense?
Yes, for seven days. Especially the small ones. You know the big amounts anyway. The small ones are the ones you estimate. And when you estimate, you like to round down.
Isn't my banking app enough?
The app shows you what was paid. It doesn't show you why. The test "Would I buy this again?" only happens when you handle the expense yourself. And the app doesn't see cash at all.
How much should I save?
I won't give you a percentage, because it depends on your income and your obligations. Start with an amount that doesn't hurt and increase it with the 1% rule until your goal is reached. The goal sets the pace, not a percentage from the internet.
What do I do with the money I save?
First you build a reserve for the unexpected, so a broken washing machine doesn't turn into an emergency. For anything beyond that, such as investments or pensions, get an independent opinion. This blog is no substitute for financial advice.
Your task for today
- Write down: Every expense from now on, for seven days. Amount, what, type, test.
- Search: Your bank statements for the last three months. Mark every subscription and every standing order.
- Cancel: One subscription you didn't use last month. Today, not at the weekend.
Your bank balance is not fate. It is the sum of your small decisions. You'll find more protocols on the DailyInspire.ch blog.
What you don't count still counts. Just against you.
More impulses
All posts
It isn't impossible. Nobody around you has done it yet.
Your "impossible" usually comes from people who never tried. What Bannister, Patton and Seneca show about it, and how to become the first in 7 days.
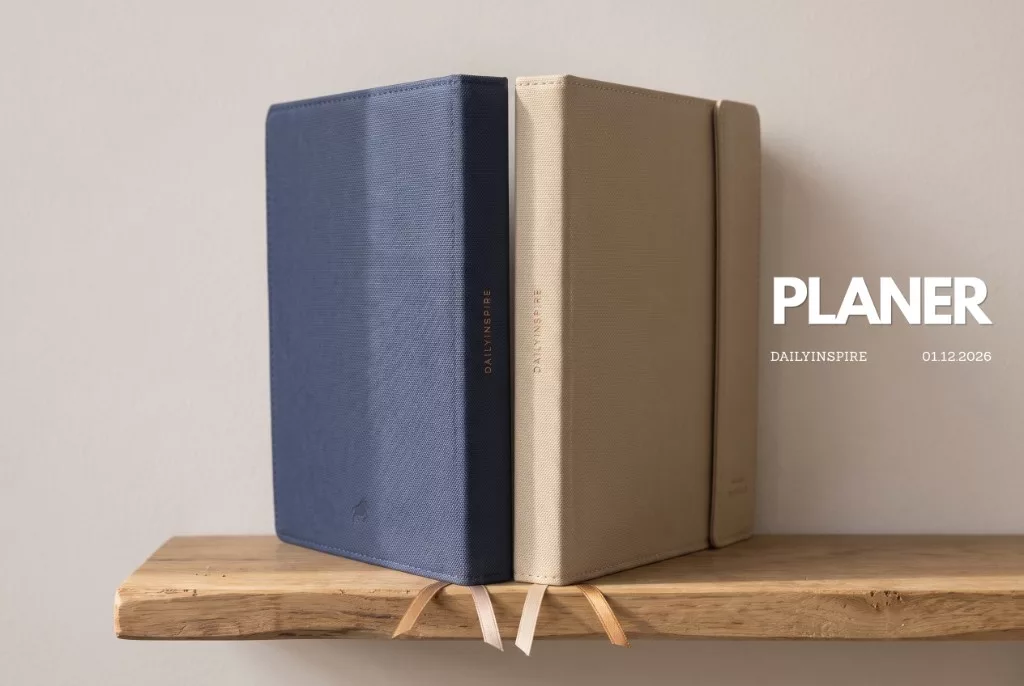
The planner is one page a day. Not a feeling.
The DailyInspire Planner is an undated year on paper: one page a day, five tasks, the line today = yesterday × 1.01. Order from next week. Join the waitlist today.
You want to be loved? Then stop waiting.
You're waiting for someone else to love first. Nine laws show why that doesn't work and how to rebuild trust, words and closeness in seven days.